The fast payout casino promise in Australia, and what sits behind it
The phrase “fast payout casino” is doing two jobs in the Australian market, and only one of them is real. On the marketing side, it advertises how quickly an offshore site will send your money back. On the legal side, that same site is offering an interactive gambling service that the Interactive Gambling Act 2001 prohibits anyone from supplying to a person physically in Australia. The honest comparison is not which offshore cashier is fastest. It is what the marketing actually delivers, what the ACMA has already done about it, and where an Australian reader who wants a shortlist of lawful options should be looking instead.
Currency and enforcement snapshot: data current as of 29 October 2026, checked against the Australian Communications and Media Authority’s published blocking round and formal warnings register.
Table of Contents
- How “fast payout” turns up in the search results
- What the law actually says about online casinos in Australia
- How the ACMA applies that prohibition
- Brand and ACMA action
- What an offshore fast-payout site actually offers the Australian reader
- How money moves on the Australian side
- What Australian banks do on their own side
- Mobile wallets and the card-rail problem
- What “trust” means on a site the ACMA has warned
- Crypto and the fast-payout pitch
- The reviewed brands, side by side
- What the comparison actually settles
- What an Australian reader who wants a shortlist can actually do
- Tax, and what an Australian reader does with a win
- Frequently asked questions
How “fast payout” turns up in the search results
The promise is the same on every reviewed brand: a deposit in, a withdrawal cleared within hours, sometimes within minutes, often through a cryptocurrency rail or an e-wallet that the site claims clears faster than a bank transfer. It is a competitive hook in a market crowded with look-alike sites, and it is the thing a punter chasing a win actually notices once they have one. The fast-payout pitch is built to be the deciding factor when two brands sit side by side on a comparison page.
What sits underneath it is harder to verify. A withdrawal advertised as “instant” still passes through whatever the cashier actually uses on the Australian end — and an Australian bank sitting on the receiving side of an offshore transfer will run its own checks, hold its own anti-fraud logic, and may not honour the speed claim at all. The brand cannot guarantee the last mile. What it can do is pick a rail that minimises it, and that is the part of the comparison that survives the marketing.
The cluster of terms that drives readers here — fast payout casino, casino fast payout, online casino fast payout, fast payout online casinos, casino with fast payout, casinos with fast payout — shares one underlying intent. The reader wants a shortlist, not a primer. They want to know which of two look-alike offshore brands will put the money back first, and whether the answer to that question makes any difference once the legal status of the offer is on the table. This page lays out that second question first.
What the law actually says about online casinos in Australia
The Interactive Gambling Act 2001, as tightened by the Interactive Gambling Amendment Act 2017, makes it an offence to provide online casino games, online pokies or in-play betting to a person in Australia. No state or territory issues a licence for these products. What is licensable is wagering on races and sport placed before the event, lotteries and keno, and that side of the market is regulated through a different set of licences — in practice the Northern Territory Racing and Wagering Commission (NTRWC), which sits behind 52 of Australia’s online bookmakers including Sportsbet, Bet365 and Ladbrokes, and which runs without full-time staff and meets once a month in Darwin.
The architecture is deliberate. The IGA targets the provider, not the individual player. Australians can be sent marketing, sign up, deposit and lose without facing prosecution themselves. The consequence is that the choice a reader has to make is not between legal offshore brands and illegal ones. There are no legal offshore online casinos for Australians. There are legal wagering sites for sports and racing, and there is a brick-and-mortar casino and pub-pokies sector. The “online casino” category the search query asks about does not exist as a licensable product in Australia, no matter what licence seal the offshore brand pastes into its footer.
The Interactive Gambling Amendment (Gambling Reform) Bill 2026 passed Parliament on 19 August 2026, with its advertising and inducement measures commencing 1 January 2027. The bill does not open the category of licensable online casino games — it tightens the existing frame around how licensed wagering is marketed. A reader landing on this page in 2026 is reading it before those measures are in force.
How the ACMA applies that prohibition
The Australian Communications and Media Authority (ACMA) is the body that turns the prohibition into something a reader sees. Three instruments do the work. The ACMA investigates complaints, issues formal warnings to named operators, and directs Australian internet service providers to block illegal sites at the network level. A blocked site is one an Australian cannot reach through a normal Australian ISP without a workaround, and that is the reason these brands have rotating domains and a stream of rebrands behind them.
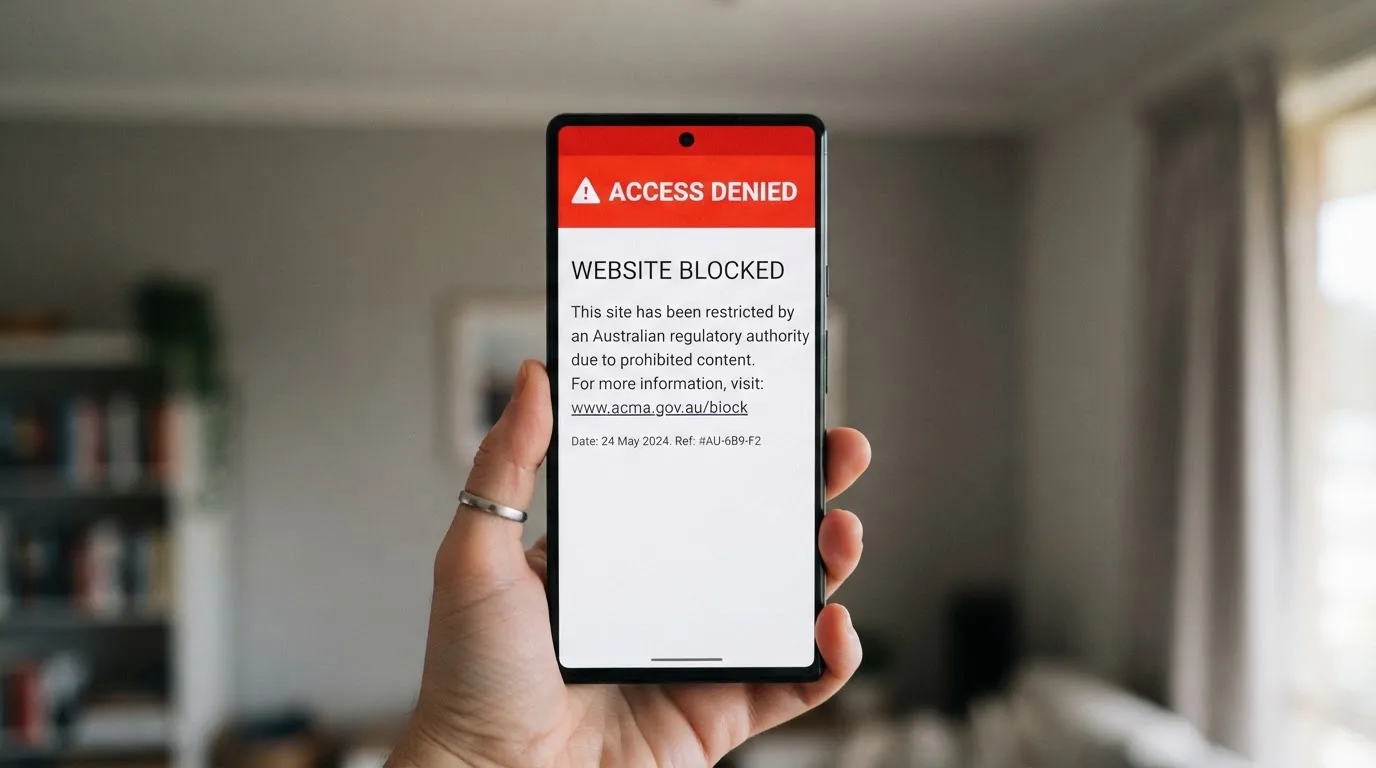
The ACMA’s blocking record is the only quantitative measure of how the prohibition is actually applied. As reported in June 2026, a total of 1,751 illegal gambling and affiliate marketing websites had been blocked since the first blocking request in November 2019, and more than 230 unlicensed gambling services had left the Australian market since enforcement was strengthened in 2017. In the round reported on 26 June 2026 alone, the ACMA asked ISPs to block a further 12: 7Signs, ChromaBet, Donbet, Duospin, Freshbet, Slots Gem, Jacks Club, Lucky Start, Pointsbetz, Spinrise, Vinyl Casino and Wildsino. The blocking rate over the period from that first request gives the shape of enforcement, and it is the page’s only honest look at how often the rule has actually been used.
The blocking rate is a band, not a single number, because the numerator and the denominator both move. Across roughly 79 months from November 2019 to the end of June 2026, 1,751 blocked sites works out to about 22 blocked sites per month on average. The range is wider than the average: some months the ACMA orders a single coordinated round, others an empty month followed by a dozen. What the band says is that enforcement is steady rather than occasional — the ACMA is using the blocking instrument as a routine tool, not as a one-off. The condition attached to the figure is that it counts sites blocked, not operators sanctioned, and the same offshore group can sit behind several domains.
The formal-warning register is the second instrument, and it is the one this page leans on most heavily. A formal warning is a published letter to a named operator; it precedes blocking but it is not blocking. The ACMA has used formal warnings against the operators behind many of the brands a search for “fast payout casino Australia” returns, and the dates and operator names are public. The table below carries that record as the ACMA published it, for the operators reviewed on this page.
Brand and ACMA action
| Brand | ACMA action and date | Operator named by the ACMA | Subject support |
|---|---|---|---|
| RocketPlay | Formal warning March 2026; earlier May 2022 warning to Dama N.V. | Pulsup Ltd (Rocketplay) | listings only — Gambling Insider |
| Level Up Casino | Formal warning May 2022 | Dama N.V. | listings only — Westpac |
| Woo Casino | Formal warning March 2025 | Dama N.V. | — |
| Spirit Casino | Formal warning May 2025 | Dama N.V. | — |
| National Casino | Formal warning July 2025 | Consolutetish S.R.L. | listings only — acma.gov.au, austrac.gov.au, betstop.gov.au |
| Bizzo Casino | Formal warning July 2025; earlier 2022 warning to TechSolutions | Consolutetish S.R.L. | listings only — Gambling Insider |
| Ignition Casino | Formal warning July 2025 | Bamboo Media | — |
| Instant Casino | Formal warning February 2025 | EOD Code SRL | listings only — EcoPayz, PayID |
| Jackbit | Formal warning April 2026 | Ryker B.V. | — |
| Casino Intense | Formal warning April 2025 | Sterplay Holding Ltd | listings only — austrac.gov.au, betstop.gov.au, Gambling Insider |
| Sky Crown | Formal warning September 2022 | Hollycorn N.V. | — |
The “Subject support” column reflects what the research sources themselves cover. A blank cell means no consulted listing covered the brand’s payment or payout infrastructure, not that the brand has none; readers should treat a blank cell as a signal that the comparison page they were reading was silent on this brand. Where sources do name a payment-method connection, that is reported only as what those listings say, not as a fact the brand has confirmed.
The shape of the table is what it is because the ACMA is the only Australian authority that has put its name to a record of action against these specific brands. A comparison of bonuses, payout times or game libraries would be drawn from affiliate marketing pages and would not survive scrutiny. The legal action is the only field on which the record is independent.
What an offshore fast-payout site actually offers the Australian reader
The contrast between marketing and mechanics is the whole reason this page exists, and the cleanest way to draw it is the contrast between two adjacent ideas. On the marketing side, an offshore brand is selling speed — instant withdrawals, “winnings in minutes”, “no pending time”. On the receiving side, an Australian bank has no obligation to honour any of those words, and a regulator has no jurisdiction to force it to.
Two practical consequences follow. First, a withdrawal that the offshore cashier marks as “approved” can still sit in the Australian bank’s queue, and the brand’s published time-to-cash stops the moment the money leaves its processor. The “fast” claim is, in most cases, a claim about the first half of the transfer, not the whole one. Second, the protections that an Australian might expect — a complaint to a regulator, a self-exclusion register that the site is bound to honour, an external dispute resolution body — are not available offshore. There is no Australian ombudsman to write to. There is no BetStop-style mechanism that binds the offshore site. The recourse a reader has is the legal system of the country the brand is incorporated in, and that is the recourse the brand picked.
It follows that the published payout time is a comparison of half-pipelines. A reader who wants to know the actual time on a real Australian bank account has to think about both halves separately — what the brand’s cashier does on its side, and what the receiving bank does on the Australian side. The next shelf on this page covers that second half, because that is the half the brand cannot influence.
How money moves on the Australian side
The rails an Australian reader can actually receive money through are narrower than the marketing suggests. Three of them dominate: Osko instant bank transfers, BPAY, and a PayID-addressed transfer. Each has a published behaviour, and that behaviour is what governs the last mile.
Osko is the instant-transfer service sitting on Australia’s New Payments Platform. Under it, a bank transfer between participating Australian banks arrives in under a minute, around the clock including weekends, whether the transfer is addressed to a BSB and account number or to a PayID. The platform went live on 13 February 2018, and is owned by New Payments Platform Australia Ltd, a non-profit company whose 13 shareholders include the Reserve Bank of Australia and the country’s major banks. The platform keeps monthly outages to no more than two minutes, and more than 25 million PayID identifiers had been registered on it as of April 2025. What Osko does on the Australian side is set the upper bound for the last mile. If an offshore cashier can send to an Australian PayID through a participating bank, the receiving-side delay collapses to seconds; if it cannot, the receiving-side delay is whatever the receiving bank does with an ordinary transfer.
A PayID-based transfer adds a check that does not exist on a BSB-and-account transfer. Paying to a PayID shows the name of the account holder before the transfer is sent, and AP+ warns that being asked to transfer money to a PayID on an illegal gambling site almost certainly means a scam site. The check is not a block; the transfer still goes through if the sender presses on. But it is the only friction the rail itself puts in the way of a misdirected payment, and the offshore brand has no control over whether its cashier shows it.
PayID-based instant transfers are available at over 100 Australian financial institutions. The breadth matters: an offshore brand can promise PayID receipt, and on the Australian side that promise either holds or it does not depending on which bank the reader banks with. A reader using one of the four majors will see it; a reader using a smaller institution may see a slower rail with PayID converted into a queued transfer.
BPAY is the other Australian-side rail a reader will see named. It is a bill-payment service in online banking, where the payer enters the Biller Code and the Customer Reference Number printed on the bill, and it has been in operation since 18 November 1997. It is available in the online banking of over 140 banks and financial institutions and is offered by over 95,000 businesses. BPAY is owned equally, via Cardlink Services Limited, by Australia’s four major banks — ANZ, Commonwealth Bank, National Australia Bank and Westpac — and runs under Australian Payments Plus (AP+), the same operator as PayID and Osko, after the September 2021 ACCC-authorised merger that brought BPAY Group, eftpos and NPP Australia together. For a withdrawal use case, BPAY is unusual: it is designed for payers sending money to a biller, not for an offshore cashier pushing money back. An offshore brand offering “BPAY withdrawals” is typically offering to push the funds into a BPAY-billed arrangement that the reader can then collect, and the speed of that path is set by the biller’s processing, not by BPAY itself.
AUSTRAC’s threshold-transaction-report rule, which requires reporting of transfers of A$10,000 or more, applies only to physical cash. Ordinary electronic bank transfers are not subject to that per-transaction reporting requirement, regardless of the amount sent. The point is small but worth stating: an Australian reader moving a five-figure withdrawal through Osko is not triggering a reporting event on the transfer itself. The brand’s KYC check is the only reporting-style friction on that side.
The reader-side takeaway from the four rails is that Osko sets the floor for the last mile. If the brand can route to a PayID through an Australian participating bank, the published “withdrawal time” stops being a half-pipeline claim and starts being a real one. If it cannot, the published figure is fiction at the Australian end.
What Australian banks do on their own side
The bank-side mechanics matter because that is where the marketing claim actually arrives or stalls. Four of the major Australian banks run gambling blocks at card level, and the design of those blocks tells the reader exactly what their own bank will and will not stop.
Westpac’s gambling block works at card level: it refuses authorisation of transactions registered under the merchant category code ‘Betting/Casino Gambling’ on eligible personal credit and debit cards. ANZ’s block, activated in the ANZ app, blocks gambling transactions made through a digital wallet such as Apple Pay on an eligible card, not just the physical card; once it is on, removing it requires a 48-hour waiting period, and the bank warns that not all gambling transactions will be blocked and that some non-gambling transactions might be blocked in error. Commonwealth Bank lets customers apply a gambling lock to eligible cards via the CommBank app, with the same caveat that it cannot guarantee all gambling-related purchases will be stopped.
The combined effect is two-sided. On the deposit side, an Australian reader with the bank-level block on will see card-based deposits refused at the merchant category code level, regardless of which offshore brand is on the other end of the transaction. On the withdrawal side, the block is irrelevant — it is the deposit rail that gets the bank-side check. The card brands themselves sit in the middle. American Express, established in 1850 and a card issuer since 1 October 1958, is a three-party scheme that issues cards and processes transactions itself, and the Reserve Bank of Australia’s July 2025 review proposes removing surcharges only on eftpos, Mastercard and Visa card transactions, leaving American Express explicitly outside the scope of the proposed surcharge ban. The card network the offshore brand uses on the deposit side is one of the variables that determines whether the bank-level block actually catches the transaction.
Mobile wallets and the card-rail problem
Apple Pay, Google Pay and Samsung Pay transactions collectively accounted for around 45% of all card payments in Australia by number by the end of 2025. Apple does not charge fees to consumers for using Apple Pay in stores, online or in apps — any surcharge comes from the merchant’s card-processing fees, not from Apple — and Apple states that transaction limits and PIN requirements for Apple Pay purchases are set by the card issuer or merchant, not by Apple itself. The point matters because a digital wallet does not change the merchant category code sitting underneath the transaction, and it does not change which bank issued the underlying card. ANZ’s gambling block explicitly catches Apple Pay transactions on an eligible card, and the bank-level block design treats a wallet payment as a card payment for blocking purposes.
The legal frame sits behind the bank-level blocks. Under the Interactive Gambling Act 2001 as amended in 2023, Australian-licensed online wagering services cannot accept payment by credit card or other credit-related products — a restriction that also constrains gambling use of linked digital wallets like Apple Pay. The prohibition bites on licensed wagering services only. An offshore casino sits outside that frame, and the bank-level blocks and card-network design do the enforcement work that the IGA does not, for the licensed side, and cannot, for the offshore side.
What “trust” means on a site the ACMA has warned
The cluster of terms that drives this page includes fast payout trusted casino and its near-twins — trusted fast payout casino, trusted fast payout casino Australia. The intent is the same: a reader wants a brand they can rely on, not just a brand that pays out fast. The trouble is that the Australian side of the question has no licensable answer in this category, and the offshore side has no independent Australian complaint body to lean on.
Three mechanisms exist that an Australian reader can actually use. First, BetStop, the National Self-Exclusion Register, has been live since August 2023 and binds Australian-licensed online and phone wagering services — an offshore casino is not connected to it. Second, the National Gambling Helpline on 1800 858 858 is free, 24/7, with chat at Gambling Help Online. Third, AUSTRAC’s reporting framework sits behind the licensed side of the market and not the offshore side, and an Australian reader who has had a withdrawal refused has no AUSTRAC escalation path that will get the money back.
What does follow from those three mechanisms is a more concrete answer to “trusted”. A brand a reader can trust is one that has been on the Australian register long enough to have been blocked or warned by the ACMA, and one whose payment rail a reader can independently verify reaches an Australian bank account through a rail the reader’s own bank will not block. The ACMA’s published formal warnings are the only field on which an independent Australian authority has named these brands. The list on this page is that record.
Crypto and the fast-payout pitch
The search terms behind this page also include fast payout crypto casino, crypto casino fast payout, fast payout crypto casinos and bitcoin casino fast payout, with fast payout bitcoin casino and bitcoin casinos fast payout as supporting queries. The intent is a reader who has decided that a digital-asset rail is the answer to the slow-bank-transfer problem, and who is looking for a shortlist of brands that take that rail seriously.
The legal frame changes that decision. Credit cards, credit-related products and digital currency are banned as payment for licensed online wagering since 11 June 2024, with penalties up to A$247,500 for operators that take them. A site asking an Australian for a crypto deposit is operating outside the Australian rules by definition, because licensed Australian wagering cannot take crypto and unlicensed offshore brands cannot lawfully serve Australians at all. The “fastest” rail on the crypto side is therefore attached to a brand that the ACMA has already acted against, on a category of product the IGA prohibits from being supplied to Australians in the first place. The crypto pitch is real speed on a rail the law does not permit.
There is a separate question of whether crypto makes an offshore brand any safer to use. The answer in the Australian frame is no, for the reason the previous shelf gave: there is no Australian complaint body for offshore brands regardless of the rail. The crypto rail does not give the reader a regulator on the Australian side, and it does not give the reader an external dispute resolution service on the offshore side. It gives the reader a transfer the offshore cashier has no incentive to delay, which is what the marketing was already promising on the e-wallet rail without the legal exposure.
The reviewed brands, side by side
The shelf below is not a ranking and not a recommendation. The ACMA itself issued a formal warning over each brand for offering prohibited services to Australians. The shelf lines them up so a reader can see what the ACMA record actually says for each, and what the consulted sources do and do not cover. The verdict on each block is the page’s own judgement of what the ACMA record means for the reader, which the dates and operator names above it do not.
RocketPlay
The ACMA issued a formal warning to Pulsup Ltd over RocketPlay in March 2026, and an earlier warning to Dama N.V. covered Rocketplay in May 2022 alongside five other brands. The 2026 warning is the one that names the current operator; the 2022 warning is the one that names the historical corporate parent. RocketPlay is the .au-facing variant of a brand that has changed hands and changed operator shells. The consulted listing coverage was a single marketing directory entry, which is not an independent assessment of the brand’s payout infrastructure. The brand is the most recent Dama N.V. successor on this list, and the operator named in 2026 is a different entity than the one warned in 2022.
The verdict: a brand whose .au-facing domain the ACMA has warned within the last twelve months, on a warning the regulator has chosen to publish. A reader cannot treat the 2022 operator warning as evidence about the 2026 operator’s behaviour, and the consulted sources do not give an independent read on what the brand’s payout time actually is. The single signal of substance is the warning itself.
Level Up Casino
Dama N.V. was warned by the ACMA in May 2022 over six casino brands — Bambet, Dazard, Level Up, Rocketplay, Wild Tornado and Cobra Casinos. Level Up is one of those six, and the operator shell behind it has not been replaced by a separately-named entity in the published record. The consulted listing coverage was a single Westpac reference, not an independent assessment of the brand’s payment infrastructure. A reader looking for “Level Up” today is looking at a brand whose Australian-facing operator was named by the ACMA four years ago, and whose consulted coverage in this set is minimal.
The verdict: an old warning whose operator is still named in current ACMA correspondence. The consulted sources do not give a read on what the brand has done since. A reader is making a decision on a four-year-old warning and a minimal source footprint.
Woo Casino
Dama N.V. was warned by the ACMA in March 2025 over Woo Casino, four years after the original 2022 warning that covered other Dama brands but not Woo. The consulted listing coverage was empty — no consulted source in this set covered Woo Casino on payout infrastructure. The brand is one of two Dama N.V. successor warnings in 2025, alongside Spirit Casino, and it sits inside a pattern of Dama N.V. operator shells the regulator has been working through over the four-year window.
The verdict: a current Dama N.V. warning, on a brand for which no independent data source provides verification. There is no third-party read on payout infrastructure to weigh against the ACMA record.
Spirit Casino
The ACMA warned Dama N.V. over Spirit Casino in May 2025, two months after the Woo Casino warning. The consulted listing coverage was empty, as with Woo Casino. Spirit and Woo are the two 2025 Dama N.V. warnings, and they sit close enough together to read as a coordinated enforcement pass rather than as separate triggers. The brand is newer on the regulator’s record than Woo, and is the most recent Dama N.V. entry alongside the March 2025 Woo warning.
The verdict: the most recent Dama N.V. entry, on a brand for which no consulted source provides independent coverage. The closeness of the two 2025 warnings suggests a single enforcement pass rather than two independent triggers.
National Casino
Consolutetish S.R.L. was warned by the ACMA in July 2025 over National Casino and Bizzo Casino. The consulted listing coverage was three-source: ACMA’s own register, AUSTRAC’s framework page and BetStop. The BetStop reference is the most telling, because BetStop binds only Australian-licensed services and a brand appearing in a BetStop-relevant listing is one whose Australian context has been touched by the self-exclusion register, even if the brand itself is not bound by it.
The verdict: a brand with multi-source coverage and a current ACMA warning, on a category of product that is not licensed in Australia. The BetStop touch is the most concrete of the three consulted listings, because it is the only one of the three that is an Australian authority.
Bizzo Casino
Consolutetish S.R.L. was warned by the ACMA in July 2025 over Bizzo Casino, alongside National Casino. Bizzo had already been the subject of a 2022 formal warning to TechSolutions (CY) Group Limited and TechSolutions Group N.V., which makes it the brand on this list with two separate ACMA actions against two different operator shells. The consulted listing coverage was a single marketing directory entry. The 2022 and 2025 warnings name different operators, which is the pattern this list shows more than once: a brand survives an operator-shell change, and the ACMA names the new shell in the new warning.
The verdict: a brand the ACMA has had to warn twice, under two different operator names. A reader looking at this brand is looking at one whose operator has changed hands once already under regulator pressure.
Ignition Casino
Bamboo Media was warned by the ACMA in July 2025 over Ignition Casino, alongside the Consolutetish warnings that month. The consulted listing coverage was empty — no consulted source in this set covered Ignition Casino on payout infrastructure. The brand sits in the July 2025 cluster of ACMA actions alongside National Casino and Bizzo, three warnings in a single month against three different operator shells.
The verdict: a brand in a clustered enforcement window, on a brand lacking independent verification of its payout infrastructure. The clustering with National Casino and Bizzo is the only signal in the record.
Instant Casino
EOD Code SRL was warned by the ACMA in February 2025 over Instant Casino. The consulted listing coverage was two-source: an e-wallet provider page and the PayID framework. The PayID touch is the most concrete, because PayID sits inside Australian Payments Plus and is an Australian-rail reference rather than an offshore reference. A brand with a PayID touch in the consulted sources is one whose cashier has been described by an Australian payment infrastructure listing.
The verdict: a brand with an Australian-rail touch in the consulted sources, and a current ACMA warning. The PayID reference is the most concrete signal on this block.
Jackbit
Ryker B.V. was warned by the ACMA in April 2026 over Jackbit and CasinOK. The consulted listing coverage was empty. The brand is the most recent entry on this list alongside RocketPlay, both April–March 2026, and the operator is one the regulator has not previously named on this list — Ryker B.V. does not appear in the 2022 or 2025 warnings in the consulted record.
The verdict: a brand with a current ACMA warning, regarding which no independent source confirms the operator’s payout infrastructure. The operator is new to the regulator’s record, which is itself a signal: the ACMA is naming operator shells it has not previously named.
Casino Intense
Sterplay Holding Ltd was warned by the ACMA in April 2025 over Casino Intense. The consulted listing coverage was three-source: AUSTRAC’s framework page, BetStop and a marketing directory. The BetStop touch is the most concrete, as on National Casino. The AUSTRAC touch is a framework reference rather than a sanction, which makes it weaker than an ACMA action but stronger than a directory listing.
The verdict: a brand with multi-source coverage and a current ACMA warning, on a category of product that is not licensed in Australia. The BetStop and AUSTRAC references are the concrete signals, and they sit alongside the ACMA warning rather than against it.
Sky Crown
Hollycorn N.V. was the subject of a formal warning published as a September 2022 PDF over its Sky Crown and Blue Leo casino services. The consulted listing coverage was empty. The warning is the oldest on this list by operator and one of the older ones by brand, and Hollycorn N.V. is the only operator on the list whose name recurs across two separately-published ACMA documents (Sky Crown and Blue Leo).
The verdict: the oldest operator warning on this list, on a brand whose operator has been named twice by the ACMA under one document. There is no third-party read on payout infrastructure to weigh against the ACMA record.
What the comparison actually settles
The shelf above settles three things and leaves a fourth open.
It settles that every reviewed brand is on the ACMA’s published register. There is no brand on this list whose status is “ACMA has not acted”. A reader landing on a comparison page that ranks these brands by payout time is looking at a comparison page whose brands are all in the same Australian regulatory bucket: warned.
It settles that the consulted sources do not give a payout-time figure for any of the eleven brands. Where they cover a brand, they cover it on a payment-method or compliance reference — BetStop, AUSTRAC, PayID, a card-network reference. None of those references publishes a withdrawal-time benchmark for any of the brands.
It settles that the ACMA record is the only field on which all eleven brands are independently comparable. The dates and operator names above are the ACMA’s own publications, and they are what the comparison is built on.
What it does not settle is the order. A reader looking for a fast-payout recommendation has no ranking to act on, because a ranking on this set of brands would be a ranking on regulatory exposure, not on withdrawal speed, and the regulatory exposure is the same across all eleven. The brands differ on which warning the ACMA has chosen to publish and on what the consulted sources do and do not cover, and that is the comparison this page is built to give.
What an Australian reader who wants a shortlist can actually do
The honest shortlist for an Australian reader who wants something that exists is not an offshore online casino. Three lawful options sit within reach, and each carries its own frame.
Licensed wagering on racing and sport, placed before the event, is licensable in Australia and is regulated through the Northern Territory Racing and Wagering Commission alongside equivalent state regimes. The brands a reader sees in that space — Sportsbet, Bet365 and Ladbrokes are the three named on this page — sit inside the IGA’s licensed carve-out, and BetStop binds them. The product is not online casino games; the comparison the reader came here to make does not transfer.
Land-based casinos and licensed pub pokies are the second lawful option. They are licensed at state and territory level, are age-restricted to 18 and over, and carry the responsible-gambling mechanisms that brick-and-mortar venues run. The product is not online, and the comparison the reader came here to make does not transfer. The payment path is the venue’s own, not an offshore cashier.
BetStop, the National Self-Exclusion Register, has been live since August 2023 and is the third option. It is not a gambling option; it is the mechanism by which a reader who wants to be excluded from licensed Australian wagering services is excluded. It does not bind offshore brands, which is the limit on its reach, but it does bind the licensed side of the market a reader may otherwise drift into. The National Gambling Helpline on 1800 858 858 is free, 24/7, with chat at Gambling Help Online, and it is the operational front door of the same regime.
A reader who has already deposited with one of the brands on this list has a different shortlist in front of them. They can self-exclude through BetStop for the licensed side, they can call the helpline for advice, and they can request their bank to apply the gambling block at card level. None of those routes recovers money already deposited with an offshore brand. None of them substitutes for the protection the licensed side would have given at the time of deposit.
Tax, and what an Australian reader does with a win
Gambling winnings of a recreational player are not assessable income under section 6-5 of the ITAA 1997, and losses are not deductible, unless the person carries on a business of gambling — and the ATO is the body whose ruling on that edge case binds. The tax position is the same whether the win came from a licensed Australian wagering site, a licensed pub pokie or an offshore casino, because the tax question is about the reader’s status, not about the brand’s status. A reader who has won on one of the brands on this list is not in a different tax position from a reader who has won on a licensed brand; the difference is in the protections on the way to a withdrawal, not in what ATO does with the result.
Frequently asked questions
What counts as a fast payout time for a casino transaction?
The honest answer is that the figure on the marketing page counts only the half of the transfer the brand controls. Once the money leaves the offshore cashier, the Australian bank’s queue and the receiving rail determine how long the last mile actually takes, and the brand cannot guarantee that part. A real benchmark is the time the money is in an Australian account, not the time the cashier marks the withdrawal as approved.
How quickly does an Osko bank transfer arrive between Australian banks?
Under Osko, a transfer between participating Australian banks arrives in under a minute, 24/7 including weekends, addressed to either a BSB and account number or a PayID. That is the floor the Australian side of the transfer can hit, and it is the figure a fast-payout brand can match only if its cashier routes through a participating Australian bank to a PayID or BSB-and-account destination.
Is it legal for an online casino to offer fast payouts to players in Australia?
No. The Interactive Gambling Act 2001 makes it an offence to provide online casino games to a person in Australia, and no Australian jurisdiction issues a licence for that category of product. The fast-payout feature does not change the legal status of the offer; it changes how quickly the offer’s winnings are returned through an Australian rail, and that rail is the part the IGA does not address.
Do faster payout claims make an offshore casino any safer to use?
No. A faster payout is a feature of the cashier, not a feature of the regulatory regime. The offshore brand is still outside the ACMA’s jurisdiction over licensed wagering, still not bound by BetStop, and still without an Australian complaint body. The payout speed is real on the cashier side and irrelevant on the protection side.
What payment method typically settles quickest into an Australian bank account?
Osko, addressed to a PayID, settles in under a minute when the receiving bank is a participating institution. The next quickest are ordinary bank transfers, whose speed depends on the receiving bank, and BPAY, whose speed is set by the biller’s processing rather than by BPAY itself. Card-based withdrawals are typically the slowest because they pass through the card network’s clearing cycle.
Where can someone check whether a payment provider is genuinely trustworthy?
The Australian-side checks are the ACMA’s blocking and formal-warning registers, the AUSTRAC framework page, the BetStop register, and the consumer guidance pages of the major Australian banks. The offshore-side checks are the licence register of the jurisdiction the brand is incorporated in, and the brand’s own published terms. None of those checks will make an offshore online casino lawful to supply to Australians; they will tell the reader which brands have been named by which authorities.